
Imagine you have managed to put aside ₦500,000 after months of discipline. You have resisted unnecessary spending, avoided some social outings and gradually built a little financial cushion.
Now comes the big question: should you leave the money in your savings account or invest it somewhere that could generate returns?
It is a decision many Nigerians face, especially as the cost of living continues to put pressure on household finances and people look for ways to protect the value of their money.
Some people believe keeping money in the bank is the safest option. Others argue that leaving money untouched in a savings account means missing opportunities to grow wealth.
Both perspectives have some truth, but neither tells the complete story.
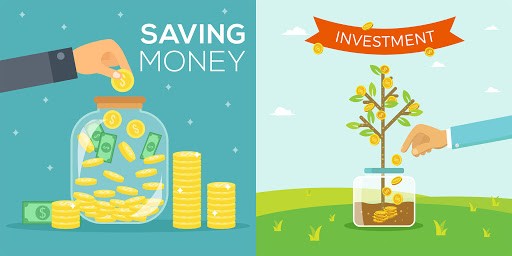
Savings and investments serve different financial purposes. One helps you prepare for emergencies and short-term needs, while the other offers opportunities to grow your money over time.
The mistake is assuming you must choose one and completely abandon the other.
A sound financial plan often needs both.
What Is Saving?
Saving means setting aside part of your income instead of spending it immediately.
The money is usually kept somewhere relatively accessible, such as a bank savings account, a suitable deposit account or another low-risk savings arrangement.
The primary purpose is to preserve money for future expenses and unexpected situations.
For example, someone who earns ₦250,000 monthly may decide to save ₦25,000 every month towards rent, school fees, medical emergencies or a planned purchase.
After 12 months, that person would have contributed ₦300,000, excluding any interest earned.
Saving is particularly useful when you need money within a relatively short period or cannot afford to expose it to significant investment risk.
It provides a financial cushion that can help prevent unexpected expenses from forcing you into debt.
What Is Investing?
Investing means committing money to an asset or financial instrument with the expectation that it may generate income, appreciate in value or both over time.
Unlike ordinary savings, investments involve some level of risk. The value of an investment can rise or fall, and returns are not always guaranteed.
Depending on your financial goals and risk tolerance, investment options may include:
- Government securities such as treasury bills and bonds.
- Money market funds.
- Mutual funds.
- Shares listed on the Nigerian Exchange.
- Exchange-traded funds.
- Real estate.
- Businesses and other productive assets.
Each option has different risks, potential returns, costs, liquidity conditions and investment periods.
For example, someone who invests in shares may benefit if the company performs well and its share price increases. However, the share price could also decline, resulting in losses if the investor sells at a lower value.
The purpose of investing is not simply to keep money somewhere. It is to put money into assets that have the potential to create additional value.
Savings vs Investment: What Is the Difference?
Although savings and investments both involve setting money aside for the future, they are designed to achieve different objectives.
1. Purpose
Savings are mainly intended to protect money and make it available when needed.
Investments are generally intended to generate returns and build wealth over time.
2. Risk
Savings accounts and other suitable deposit products generally offer more predictable balances, although inflation and applicable bank charges can reduce purchasing power.
Investments carry varying levels of risk. Some are relatively conservative, while others can experience significant price fluctuations or losses.
3. Accessibility
Savings are usually easier to access, depending on the account and withdrawal conditions.
Investments may require you to wait for maturity, sell an asset or comply with withdrawal conditions before receiving your money.
4. Returns
Savings accounts may pay interest, depending on the product and prevailing terms.
Investments may offer higher potential returns, but those returns are uncertain and depend on the asset, market conditions and investment period.
5. Time horizon
Savings are particularly useful for immediate needs and short-term goals.
Investments are often more suitable for medium- and long-term financial objectives, although some investment products have shorter maturities.
The important point is that savings and investments are not competitors. They are financial tools designed for different jobs.
Why You Should Save Before Investing
One common financial mistake is rushing into investments without first creating a financial safety net.
Imagine you have invested ₦300,000 in shares, expecting the value to increase over time.
A few weeks later, you suddenly need ₦100,000 to handle an emergency.
If the market has fallen, you may be forced to sell your shares at a loss simply because you need immediate cash.
This is one reason emergency savings matter.
Before committing significant money to investments, consider building an emergency fund that can cover essential expenses for approximately three to six months.
The appropriate target depends on your income stability, family responsibilities, health and other financial circumstances.
If your income is irregular or you support several dependants, you may need a larger financial cushion.
An emergency fund should generally be kept somewhere relatively safe and accessible rather than in assets that could lose value or take time to convert into cash.
Saving first does not mean you must wait until you have accumulated a huge amount before investing.
You can build your emergency fund and begin investing small amounts at the same time, provided your essential expenses and immediate obligations are covered.
When Should You Put Your Money in Savings?
There are situations where saving is more appropriate than investing.
1. When You Are Preparing for an Emergency
Unexpected medical bills, job losses, urgent repairs and family emergencies can happen without warning.
Having accessible savings can help you handle these situations without selling investments or borrowing money.
2. When You Have a Short-Term Financial Goal
If you are planning to pay school fees, renew your rent, purchase equipment or fund a wedding within the next few months, keeping the money in a suitable savings product may be more appropriate.
You do not want to expose money needed soon to unnecessary market fluctuations.
3. When Your Income Is Unstable
Freelancers, commission-based workers, entrepreneurs and people with irregular income may need to prioritise accessible savings.
A financial cushion can help cover essential expenses during months when income is lower than expected.
4. When You Cannot Afford to Lose the Money
If losing your principal would affect your ability to pay rent, feed your family or meet other important obligations, that money should not be exposed to significant investment risk.
The amount you can afford to invest should be considered separately from the money required to maintain your financial security.
When Should You Consider Investing?
Once your immediate financial needs are under control, investing can become an important part of your financial plan.
Here are situations where it may make sense.
1. When You Have Long-Term Financial Goals
If you are planning for retirement, long-term wealth creation, future education expenses or financial independence, investing may help you work towards those objectives.
Longer investment periods can provide more opportunity for returns to accumulate, although they do not eliminate the risk of losses.
2. When You Have Built an Emergency Fund
Having accessible savings reduces the likelihood of being forced to sell investments at the wrong time.
It also gives you more flexibility to remain invested through temporary market declines.
3. When You Want Your Money to Generate Returns
Keeping all your money in an ordinary savings account may not be enough to achieve certain financial goals.
Depending on the product, investing can provide interest income, dividends, rental income or capital appreciation.
However, the returns should always be assessed alongside the risks, fees and potential tax obligations.
4. When You Understand the Investment
You should never invest money simply because someone claims an opportunity is profitable.
Before committing funds, understand what you are buying, how it generates returns, what could cause losses and how you can access your money.
If you cannot explain how an investment works, take time to research it before proceeding.
Investment Options Nigerians Can Consider
Nigeria has several investment options, but they are not equally suitable for every investor.
Understanding their basic features can help you make more informed decisions.
1. Treasury Bills
Treasury bills are short-term government debt securities issued by the Central Bank of Nigeria on behalf of the Federal Government.
Investors purchase them at a discount and receive the face value at maturity.
They are commonly considered relatively low-risk naira investments, but they are not entirely risk-free. Returns, access conditions and the effects of inflation should be considered.
2. Government Bonds
Government bonds are debt instruments through which investors lend money to the government for an agreed period.
They generally pay interest according to their terms and return the principal at maturity.
However, investors who sell before maturity may receive more or less than they originally invested, depending on prevailing market conditions.
3. Money Market Funds
Money market funds pool money from investors and invest in relatively short-term instruments such as treasury bills, commercial papers and other eligible money market securities.
They may provide a convenient way to access a professionally managed portfolio.
However, they are investment products, not ordinary bank savings accounts. Returns are not necessarily fixed or guaranteed, and investors should review the fund’s fees, risks, redemption terms and regulatory status.
4. Shares
Buying shares means purchasing ownership in a company.
Investors may benefit from dividends and increases in share prices.
However, share prices can fluctuate significantly, and a company may perform poorly or fail to pay dividends.
Shares are generally better approached with an investment horizon and risk tolerance that can accommodate market movements.
5. Mutual Funds and Exchange-Traded Funds
These investment products allow investors to gain exposure to a collection of assets rather than selecting every investment individually.
Some funds focus on shares, others on bonds or money market instruments, while some combine different asset classes.
They can provide diversification, but their performance depends on the assets they hold, their costs and prevailing market conditions.
6. Real Estate
Investing in property may generate rental income or capital appreciation.
However, property requires careful due diligence, significant capital in many cases and consideration of legal documentation, maintenance, taxes and other expenses.
Real estate is also less liquid than many financial investments. Selling a property can take time.
How Inflation Affects Your Savings and Investments
One important reason people consider investing is inflation.
Inflation refers to a general increase in the prices of goods and services over time.
Imagine you have ₦500,000 in a savings account today.
The balance may remain ₦500,000, but if food, transportation, rent and other essential expenses become more expensive, that money may buy fewer things in the future.
This means the purchasing power of your money can decline even when its nominal value remains unchanged.
The same issue affects investments.
An investment may generate a positive return but still fail to preserve purchasing power if its return is lower than inflation after considering relevant fees and taxes.
For example, if an investment generates a 10 per cent annual return while inflation is 15 per cent, the investor has earned a positive nominal return but experienced a negative return in purchasing-power terms.
This is why investors should consider real returns, not just the amount of money an investment appears to generate.
However, trying to beat inflation should not push anyone into reckless investments or schemes promising unrealistic returns.
Should You Save and Invest at the Same Time?
For many people, the most sensible approach is to do both.
You do not have to wait until you are wealthy before investing, and you do not have to invest every available naira to grow your money.
The key is to divide your money according to your financial priorities.
For example, imagine a Nigerian worker earns ₦300,000 monthly after deductions.
After paying essential expenses, the worker has ₦40,000 available for financial goals.
One possible arrangement could be:
| Financial goal | Monthly amount |
|---|---|
| Emergency savings | ₦15,000 |
| Long-term investments | ₦15,000 |
| Short-term savings goals | ₦10,000 |
| Total | ₦40,000 |
This is only an illustration, not a universal formula.
Someone with an incomplete emergency fund may need to direct more money towards savings. Another person with stable finances and existing reserves may be able to allocate more towards investments.
Your financial situation should determine the balance.
Mistakes to Avoid When Saving and Investing
Even people who understand the difference between savings and investments can make decisions that weaken their financial position.
Some common mistakes include:
1. Investing emergency money: Money needed for urgent expenses should not be placed in assets that could lose value or become difficult to access.
2. Keeping all your money in low-interest savings indefinitely: While savings are important, relying entirely on them may make long-term wealth creation more difficult.
3. Chasing unrealistic returns: Promises of guaranteed, unusually high profits should be treated with serious caution.
4. Investing without understanding the risks: Never commit money to a product simply because friends, influencers or online promoters recommend it.
5. Ignoring fees and taxes: Charges, management fees and applicable taxes can reduce the returns you actually receive.
6. Putting all your investments in one place: Concentrating your money in a single company, asset or opportunity can expose you to unnecessary risk.
7. Using borrowed money to invest without understanding the consequences: Investment losses do not remove your responsibility to repay a loan.
8. Failing to consider your time horizon: Money needed in a few months should not automatically be placed in investments designed for long-term growth.
How to Decide Where Your Money Should Go
Before choosing between saving and investing, ask yourself a few important questions.
- When will I need this money?
- Do I have an emergency fund?
- Can I afford to lose some of this money?
- Do I understand the risks of the investment?
- What returns am I expecting, and are they realistic?
- How easily can I access the money?
- Are there fees, penalties or tax obligations?
- Does this decision support my financial goals?
Your answers can help determine whether the money should remain in savings, be invested or be divided between both.
You May Like: How To Price Your Products Without Scaring Away Customers
For investment products in Nigeria, also check the relevant regulatory status. For example, verify eligible capital market operators and registered collective investment schemes through the Securities and Exchange Commission. Understand the product documents and avoid sending money to unverified individuals or accounts.
The Best Financial Strategy Is Not Choosing One Over the Other
Savings and investments are not enemies.
Savings provide financial security, help you handle emergencies and prepare for expenses you know are coming.
Investments provide opportunities to generate returns, grow wealth and work towards longer-term financial goals.
The mistake is treating one as a complete replacement for the other.
A person who invests everything without maintaining accessible savings may be forced to sell assets when emergencies arise. Someone who saves everything but never considers suitable investments may struggle to grow wealth over the long term.
The right balance depends on your income, responsibilities, financial goals, risk tolerance and the period within which you need the money.
You do not need millions of naira to begin making better financial decisions. Start with what you can afford, build your financial cushion gradually, understand your investment options and avoid opportunities you cannot properly evaluate.
Ultimately, the question is not simply whether you should save or invest.
It is knowing which part of your money should be protected, which part can be put to work and how both can help you build a more secure financial future.